
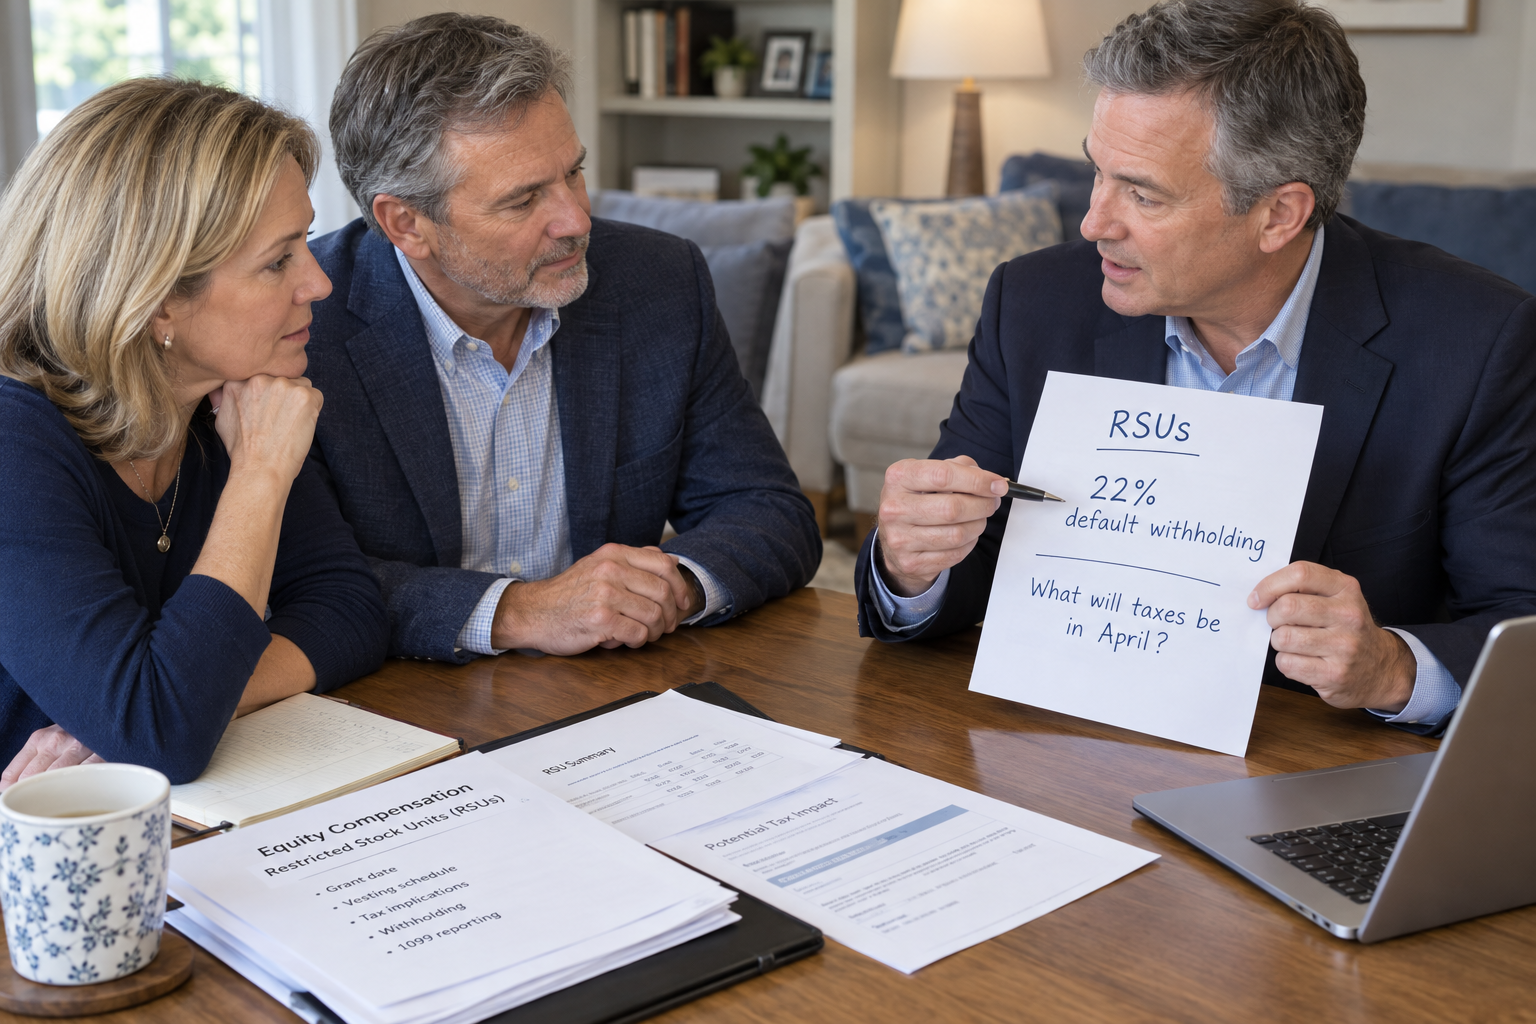
For a lot of people, restricted stock units (RSUs) can be serious wealth that shows up outside a paycheck — and it’s tied to the company they spend all day at. Two of our advisors break down how RSUs work, the tax surprises that catch people every year, and how to make a clear-eyed decision about the money.
Key TakeawaysWhen do I owe tax on my RSUs? At vesting. The value of the shares that vest is taxed as ordinary compensation, just like salary. Your company usually withholds shares to cover it, but the default 22% federal rate is often too low for high earners, which is why so many people meet a surprise bill in April. Should I hold my company stock or sell it? Reframe the question: if that same value had landed in your bank account as cash, how much would you choose to buy in your employer’s stock? For most people the honest answer is “less…maybe none.” Selling as shares vest is how many of our clients keep one company from dominating their net worth. What should this money do? The clients who do best tie their equity comp to a goal — funding college, paying off a mortgage, retiring early — instead of letting it sit in a single stock. The plan turns a volatile grant into durable freedom. |
__________________________________________________________________
When a client tells us their RSUs are about to vest, most people expect the conversation that follows to be about numbers, but it’s not. RSUs can be a serious — and sometimes the first — source of wealth that shows up outside a regular paycheck. That money is also tied to the company where they work every day, which makes the decision more tangled than a typical investment. Regardless of someone feels about their employer, sorting out what to do with RSUs is part tax question, part investment question, and part something more personal than either.
What an RSU Is
Start with the basics. A restricted stock unit is a grant of company stock that’s “restricted” until certain conditions are met, like staying with the company for a set period, an IPO, an acquisition, change in control, or performance goal. Unlike a stock option, there’s nothing to buy and no cash to put up. Unlike an employee stock purchase plan (ESPP), you’re not buying shares at a discount. An RSU is pure compensation, paid in stock. When the restrictions lift, the shares are simply yours.
How a grant becomes yours. The grant date starts a clock, and the shares vest on a schedule — monthly, quarterly, or annually. A grant of 8,000 units might vest 1,000 a quarter over two years; another of 12,000 might vest monthly over four. At many companies, especially at senior levels, a new grant is started every year, so vesting schedules stack and overlap over time.
A note for private companies. At a private company, vesting often comes with a “double trigger.” The first is time — you stay long enough for the shares to vest. The second is a liquidity event, such as the company going public or a change in control. Until that second trigger, you can’t simply log in and sell. RSUs can quietly stack up, worth nothing on paper, then can change enormously in value very quickly.
A Common RSU Tax Surprise
Vesting is a taxable event. The moment shares vest, their value is taxed as ordinary income and shows up on your W-2, just like salary or a bonus. That value also becomes your cost basis going forward. If you sell later, only the gain or loss from the vesting price is a capital gain or loss — the vesting itself is already taxed as compensation.
Why withholding leaves a gap. Companies typically withhold shares to cover taxes at a default 22% federal rate. The problem is that RSUs stack on top of salary and bonus, and many recipients are already in the 32%, 35%, or even 37% bracket. Withholding 22% against income taxed at 37% leaves a tax shortfall — and it shows up on your return the following April.
Who gets caught. The people most often surprised see “taxes withheld” and assume it’s handled. For anyone who receives a large sign-on grant, or someone newly promoted whose pay suddenly tilts heavily toward stock — their salary barely moves, but the equity comp balloons. In most cases our clients have other assets to cover the higher tax bill, so it’s manageable. Manageable, though, is not the same as pleasant.
What to do about it. Sometimes the answer is to ask payroll to withhold more so there’s no gap come April. Sometimes platforms for stock management allow employees to adjust the percentage withheld. Sometimes it’s the opposite: cover the difference through estimated payments or other assets rather than over-withholding and effectively handing the IRS an interest-free loan. Reasonable planners weigh that trade-off differently. What matters is that the bill is expected and planned for — the goal is no surprises, not zero taxes.
One Stock, Your Paycheck, and Your Net Worth
Often, many people can end up with a concentration problem. Your salary rides on one company. Your bonus does too. So does an ESPP, and now, a growing pile of vested stock. A large share of your financial life can end up betting on a single company — the same company whose fortunes already drive your income.
A reframe that cuts through it. A great clarifying question is: if you’d been handed that value as cash instead of stock, how much of it would you choose to buy in your company’s shares? Most people answering honestly, say far less than the actual amount — often none. The cleanest way to resolve this is to have the RSU sell at vest. Because you never see the stock hit your account, only the cash, selling promptly can be the cleanest way to break the emotional tie to a position you wouldn’t have chosen to build from scratch.
“I believe in my company.” We hear this often, and it’s understandable. People want to believe in what they’re working for. There can be real value in taking that belief and setting it in a broader context. How do you think the stock will perform well relative to other alternatives — your sector, the S&P 500, the global market? At what point would you feel you owned too much of one stock — 5%, 10%, 20%? An undefined, unbounded position is the risk, not the conviction. We can’t know the future either; a concentrated position might keep climbing. We’re not predicting, we’re managing risk.
Sell-to-cover versus sell-all. At vesting you generally have two paths. Sell-to-cover sells just enough shares to pay the tax and leaves the rest as stock — which quietly grows your concentration. Sell-all (or “sell at vest”) sells the whole tranche as it vests and allows you to redeploy the proceeds into a diversified portfolio. Many of our clients set vesting to sell automatically, so the decision isn’t re-litigated every quarter, and the position never has a chance to snowball.
Related: Smart Diversification Strategies for Business Owners
Trimming a Concentrated Position Without a Tax Headache
Match gains with losses. For clients who’ve already built up a large position, one tool is to sell some shares at a gain and others at a loss in the same year, netting the two so a meaningful trim can be close to tax neutral. It won’t erase every dollar of tax, but it can take risk off the table without a large bill.
Think in portions, not all-or-nothing. Selling doesn’t have to be a single leap. Often, it can be useful to sell enough to lock in a specific goal — fund a child’s college, for instance — and let the remainder ride if you choose. If it climbs, you can sell more later. If it falls, you’ve already secured what mattered most.
Income and giving strategies. For the right situations it can be advantageous to evaluate more complicated strategies such as a covered-call approach to generate income while trimming a position. For the charitably inclined, donating appreciated shares to a donor-advised fund (DAF) can also be tax-efficient. However, if the shares are recently vested and still short-term, your charitable deduction is limited to the lower of fair market value or your cost basis, so it’s usually worth holding at least a year before donating those shares.
Don’t let the tax tail wag the investment dog. It’s tempting to hold a recently vested share for months just to turn a short-term gain into a long-term one. Run the numbers, though, and the cushion is often thin. In one case we found the stock only had to fall about 3% while waiting for the lower capital gains rate to leave the client worse off than simply selling. For recently vested shares, waiting for the tax break can cost more in market risk than it saves in tax. Despite all of this, it’s important to remember that capital gains are a good problem to have – they mean the investment made money.
Related: Tax-Loss Harvesting
Related: How Donor-Advised Funds Can Help High Achievers Build Lasting Charitable Impact
Trading Windows, Blackout Periods, and Insider Rules
If you’re considered an insider at a public company, when you can sell is not entirely your choice. Employees often can only trade during open windows, with blackout periods around earnings and other sensitive events. One tool worth understanding is a 10b5-1 plan, which lets you schedule sales in advance, so trades execute automatically on a preset schedule — removing both the temptation to time the market and much of the compliance risk. After an IPO, employees also typically face a lockup period before they can sell at all, commonly around six months.
Turning Equity Into Freedom
We don’t tell clients they made the right or wrong call. “Right” and “wrong” are the wrong frame. We can’t know the future — and we’d never pretend to. We all make the best decisions we can with the information in front of us, then come back next time with fresh eyes and ask: how are you feeling now, and what percentage of your portfolio is this position today? If a client sells and the stock keeps climbing, they didn’t get it wrong. If they hold and it falls, they didn’t get it wrong either.
Watch out for recency bias. The reason a position is worth a lot is usually that it has gone up recently, which makes it feel obvious it will keep going. History is less cooperative. For every company that compounds for decades, there are many more that skyrocket after an IPO and never see that share price again. Individual stocks carry real risk, especially when they’ve done well lately.
Two clients, one fork in the road. Once, we had two families who worked at a company that went public; both had RSUs that were worth nothing until suddenly they both faced a windfall. We ran each through the same exercise, mapping sale prices to goals: sell here and you fund these things; sell higher and you unlock the stretch goals; sell lower and some goals come off the table. One family decided the price already funded most of what mattered — they sold, funded college accounts, paid off their mortgage, and set themselves up to retire in their fifties. The other believed there was room to run and held for the stretch goals. Although the stock initially rose, within a couple of years the stock fell from roughly $100 a share to about $10. They were young, with years of earning ahead, so they could afford the risk, and their story isn’t over. Their experience is illustrative of the importance of not letting a dream quietly turn into a bet you can’t afford to lose.
Don’t anchor to a number. This matters most before an IPO, when a private company’s own estimate of what a share is “worth” tends to run high. Someone close to our team expected a pre-IPO grant to be worth around $60,000; a realistic estimate was closer to $10,000; it eventually settled near $12,000. Whatever the company tells its employees, the market decides later — a number which often lands well below what was expected. Decide what matters to you before the number is real, and you’ll make a calmer decision once it is.
For the family that sold at a price that funded their goals, the RSUs did exactly what equity comp is meant to do. A volatile grant became a paid-off mortgage, funded college accounts, and a genuine path to early retirement. That’s the whole point, because money is never the goal. What it lets your family do — the security, the choices, the time — is.
Related: Retirement Planning for High Achievers
Where an Advisor Helps and Where to Start
The coordinated view. Managing equity comp well means looking at withholding, vesting schedules, gain-and-loss matching, charitable timing, and your actual goals all at once. On their own, each piece is manageable; together is where the value shows up. For one client with a large, concentrated technology position and roughly seven figures vesting each year, we changed the vesting so shares sell at vest, matched gains against losses to keep a trim close to tax-neutral, evaluated income and giving strategies, and tied every decision back to what the family wanted the money to do.
Your first step. If you have shares vesting this year and no plan for them, start here: find your vesting schedule, check what your company is actually withholding, and write down what you’d want this money to accomplish if it were cash sitting in your account. That’s usually enough to turn a vague “I should probably do something” into a real conversation.
Related: Our Process
Not working with TNLPG yet? Schedule a complimentary SWOT Session to talk through your equity comp before the next vest — so the next time your RSUs turn into real money, you already know what you want them to do.